Category: Insolvency

  • Are Directors’ Salaries Safe During Insolvency? Decoding Section 66 of IBC

    Are Directors’ Salaries Safe During Insolvency? Decoding Section 66 of IBC

    MANU/NL/0108/2026 NCLAT, New Delhi Decided 03.03.2026 Section 66, IBC 2016

    How the NCLAT’s 2026 ruling in Rakshit Dhirajlal Doshi & Ors. vs. Chirag Shah redraws the line between a director’s legitimate paycheck and a fraudulent siphoning of funds.

    Every director who has ever drawn a salary from a company that later slid into insolvency has, at some point, felt the cold sweat of a simple question: can this be clawed back? The Insolvency and Bankruptcy Code, 2016 gives liquidators and resolution professionals a formidable weapon in Section 66 — the power to unwind transactions carried out with intent to defraud creditors. But a weapon this powerful, wielded loosely, can turn every rupee of directors’ salaries during insolvency into a suspect. The NCLAT’s decision in Rakshit Dhirajlal Doshi and Ors. vs. Chirag Shah is a rare, closely-reasoned judgment that pulls that weapon back within its proper limits — and in doing so, offers a masterclass in how Section 66 ought to actually work.

    This is a judgment every director, resolution professional, liquidator, and insolvency lawyer needs to read closely, because it exposes just how thin the line is between honest remuneration and fraudulent trading — and how easily that line gets blurred without rigorous proof.

    The Case at a Glance

    ForumNational Company Law Appellate Tribunal, New Delhi
    BenchAshok Bhushan, J. (Chairperson) & Barun Mitra, Member (T)
    Corporate DebtorDoshion Water Umbrella Pvt. Ltd.
    CIRP Commencement01.07.2022
    Amount Impugned by AARs. 26.42 lakhs
    Amount NCLAT Ordered RefundedRs. 4.78 lakhs
    Provision in QuestionSection 66, IBC 2016 (Fraudulent / Wrongful Trading)

    The Backdrop: A Transaction Audit Flags Two Payments

    When Doshion Water Umbrella Pvt. Ltd. entered CIRP, the Resolution Professional engaged M/s Pipara & Company as Transaction Auditor. Their report flagged two sets of payments to the erstwhile directors (the Appellants): managerial remuneration aggregating Rs. 23.64 lakhs, and a separate sum of Rs. 2.78 lakhs. The RP filed a Section 66 application. By the time it reached final hearing, the RP had been replaced by a Liquidator following the company’s move into liquidation.

    The Adjudicating Authority (NCLT, Ahmedabad) sided fully with the Liquidator, holding that the entire Rs. 26.42 lakhs had been withdrawn “under the guise of managerial remuneration” in violation of Section 66, and ordered a complete refund. The directors appealed — and the NCLAT’s re-examination of the facts tells a very different story.

    The Battle Lines

    Appellants’ Case

    Rested on a deceptively simple internal-consistency argument: they had drawn no salary at all since April 2019. When they eventually claimed remuneration for April 2020 to June 2022, the very same Resolution Professional admitted those claims as legitimate. So how could remuneration claimed by the same directors, for the same role, for the immediately preceding financial year (2019–2020), suddenly become “fraudulent”? They also pointed to the absence of any other employees or operational creditors left unpaid in preference, and leaned on Anuj Jain vs. Axis Bank Ltd. to insist that fraudulent intent must be pleaded with specific material facts — not inferred from vague suspicion.

    Liquidator’s Case

    Built on circumstantial optics: the remuneration was drawn immediately upon receipt of funds from a sister concern (M/s Penta Aqua Pvt. Ltd.); the company was financially stressed with statutory dues like TDS unpaid; and the directors, as insiders, should have held themselves to a higher standard of restraint. Direct proof of fraud, it was argued, isn’t necessary — circumstantial evidence of self-payment during distress is enough.

    Inside the NCLAT’s Reasoning: Five Principles That Matter

    1

    Section 66 Demands Proof “Beyond Reasonable Doubt” — Not Suspicion

    The Tribunal opened its analysis (Para 9) with a statement that deserves to be underlined by every insolvency practitioner: to establish fraudulent or wrongful trading, the degree of proof required is of an “unimpeachable nature and beyond reasonable doubt.” Mere suspicion, however well-founded it may feel to a Liquidator staring at a stressed balance sheet, is not enough. Section 66 is not meant to be a convenient mop-up clause for every payment a liquidator finds distasteful in hindsight.

    2

    You Can’t Admit the Same Transaction Twice and Call It Fraud Once

    The RP had admitted the directors’ remuneration claims for FY 2020–2021 as legitimate, evidenced by IBBI claims portal records, the Transaction Audit Report, and supporting ledgers (Para 10). Having accepted that the directors genuinely rendered managerial services, the Liquidator could not simultaneously call structurally identical payments for the preceding year fraudulent — absent any allegation of falsified records.

    3

    Timing Isn’t What You Assume It Is — Read the Bank Statement, Not the Narrative

    The Liquidator leaned heavily on proximity — the suggestion of last-minute, insolvency-eve withdrawals. But the bank statements (Para 11) showed the Rs. 21.64 lakh payment was withdrawn on 31.03.2021 — more than fifteen months before the Section 7 petition was even admitted. The narrative of “eleventh-hour siphoning” didn’t survive contact with the primary evidence.

    4

    Routing Funds Through a Sister Concern Is Not, By Itself, a Badge of Fraud

    The Tribunal rejected the theory that receiving funds from a related entity and immediately drawing remuneration from it was inherently suspicious. Inter-group fund routing for revenue generation is “standard business practice,” and fraudulent intent must be backed by specific pleading and proof (Para 13) — not inferred from a related-party relationship alone.

    5

    Unpaid TDS Doesn’t Retroactively Poison a Separate, Legitimate Payment

    The Liquidator argued that failure to deposit TDS while the account was NPA made the remuneration payments preferential too. The NCLAT rejected this, holding non-payment of tax obligations and payment of remuneration to be “two separate buckets or categories of payments” (Para 14).

    The Real Doctrinal Contribution: Untangling Section 43 from Section 66

    Beyond the facts of this case, the NCLAT delivered its most valuable service to IBC jurisprudence in Para 15, calling out the Adjudicating Authority for casually conflating preferential transactions (Section 43) with fraudulent trading (Section 66).

    Section 43 targets preference — a debtor putting one creditor ahead of similarly situated others in the twilight period before insolvency, tested through a largely objective, look-back framework.

    Section 66, by contrast, is anchored entirely in intent to defraud — a far more serious and subjective threshold, requiring specific material facts to be pleaded and proved.

    Blurring these two provisions is not a technicality — the consequences that flow from each are materially different, and tribunals cannot use the softer, more mechanical test under Section 43 to backfill a Section 66 case that fails on intent. This clarification alone makes the judgment a valuable precedent well beyond its specific facts.

    The One Payment That Didn’t Survive — And Why It’s the Most Interesting Part

    Of the Rs. 26.42 lakhs originally clawed back, the NCLAT freed up Rs. 21.64 lakhs (over 80% of the disputed amount) — but it did not extend the same relief to a smaller Rs. 2 lakh cheque. Why? The cheque was drawn one day before CIRP commenced, but was cleared only after the CIRP admission order.

    30.06.2022
    Cheque drawn
    01.07.2022
    CIRP begins — moratorium wall
    Post-CIRP
    Cheque cleared — refund ordered

    The Tribunal held it “cannot rule out the factum that the Appellant was having knowledge that insolvency of the Corporate Debtor was imminent or was inevitable,” and ordered this amount restored (Para 12). Combined with the Rs. 2.78 lakhs the directors themselves conceded (a post-CIRP appropriation caught by the moratorium), the final refund liability came down to Rs. 4.78 lakhs.

    “Knowledge that insolvency was imminent or inevitable” sounds less like intent to defraud under Section 66(1), and more like the wrongful-trading standard under Section 66(2).

    This distinction rewards close reading. The judgment does not expressly separate its analysis along these sub-sections, and a sharper practitioner should note that the reasoning for the Rs. 2 lakh clawback leans on a lower, more objective threshold than the “beyond reasonable doubt” fraud standard applied everywhere else. In practice, the operative bright line is simpler and far more useful: once the moratorium clock starts ticking, the date of clearance — not just the date of drawing — determines the fate of a payment.

    The Scorecard

    TransactionAmountDateOutcome
    Managerial remuneration (FY 2019–20)Rs. 21.64 lakhsWithdrawn 31.03.2021Relief Granted
    Managerial remuneration (FY 2019–20)Rs. 2 lakhsCheque cleared post-CIRPRefund Upheld
    Project advisory servicesRs. 2.78 lakhsAppropriated 02.07.2022Refund Upheld

    Distilled Wisdom: What Every Stakeholder Should Take Away

    For Directors & Promoters

    Consistency and documentation are your best defence. Remuneration regularly recorded and treated uniformly across years is hard to recharacterise as fraud later. But the moratorium is an absolute wall — stop all outward transactions the moment insolvency proceedings are admitted, not merely when cheques are signed.

    For Insolvency Lawyers

    Keep Section 43 and Section 66 analytically separate. Don’t let the language of “preference” creep into a fraudulent trading finding, or vice versa.

    Conclusion

    Rakshit Dhirajlal Doshi vs. Chirag Shah is ultimately a judgment about proportionality and precision in insolvency litigation. It affirms that Section 66 remains a serious, high-threshold provision reserved for genuine dishonesty — not a catch-all recovery tool against every director who happened to be paid while their company was in distress.

    For a question as consequential as whether directors’ salaries during insolvency can survive scrutiny, the NCLAT’s answer is clear: legitimate remuneration, properly documented and consistently treated, is safe — but the moment the moratorium bell rings, every subsequent rupee needs to stay firmly on the company’s side of the ledger.

    Frequently Asked Questions

    Can a director’s salary be clawed back during company insolvency in India?

    Only if the Resolution Professional or Liquidator proves, with specific and cogent evidence, that the payment was made with intent to defraud creditors under Section 66 of the IBC. Genuine remuneration for actual services rendered, recorded properly in company books, is generally protected — as the NCLAT confirmed in Rakshit Dhirajlal Doshi vs. Chirag Shah.

    What is the difference between Section 43 and Section 66 of the IBC?

    Section 43 deals with preferential transactions — payments that put one creditor ahead of similarly placed creditors, tested through an objective look-back framework. Section 66 deals with fraudulent or wrongful trading and requires proof of actual intent to defraud creditors, a much higher and more subjective threshold.

    What standard of proof is required to establish fraudulent trading under Section 66?

    The NCLAT held that the evidence must be of an “unimpeachable nature and beyond reasonable doubt.” Mere suspicion, presumption, or circumstantial financial distress is not sufficient to attract Section 66.

    Does receiving company funds from a sister concern automatically make a director’s payment fraudulent?

    No. The NCLAT held that routing funds through a related or sister concern is standard business practice and cannot, by itself, be treated as evidence of fraudulent intent unless accompanied by specific pleadings and proof of wrongdoing.

    If a company doesn’t pay statutory dues like TDS, does that make other payments to directors fraudulent?

    Not automatically. The NCLAT ruled that unpaid statutory dues and remuneration payments are separate categories of transactions, and a default on one does not by itself establish fraudulent intent behind the other.

    What happens to payments made after the CIRP moratorium begins?

    Payments appropriated or cleared after the commencement of the moratorium under Section 14 of the IBC are generally inadmissible and recoverable, regardless of when they were initiated. A cheque drawn before CIRP but cleared after CIRP admission was ordered to be refunded in this case.

    Can an RP challenge a transaction as fraudulent if it had earlier admitted a similar claim for a different period?

    The NCLAT indicated this is difficult to justify. If an RP admits a remuneration claim for one financial year as legitimate, it undermines a later argument that a structurally identical payment for an adjacent period was fraudulent, absent evidence of falsified records.
  • CFO and Whole-Time Director: One Person, Two Roles?

    CFO and Whole-Time Director: One Person, Two Roles?

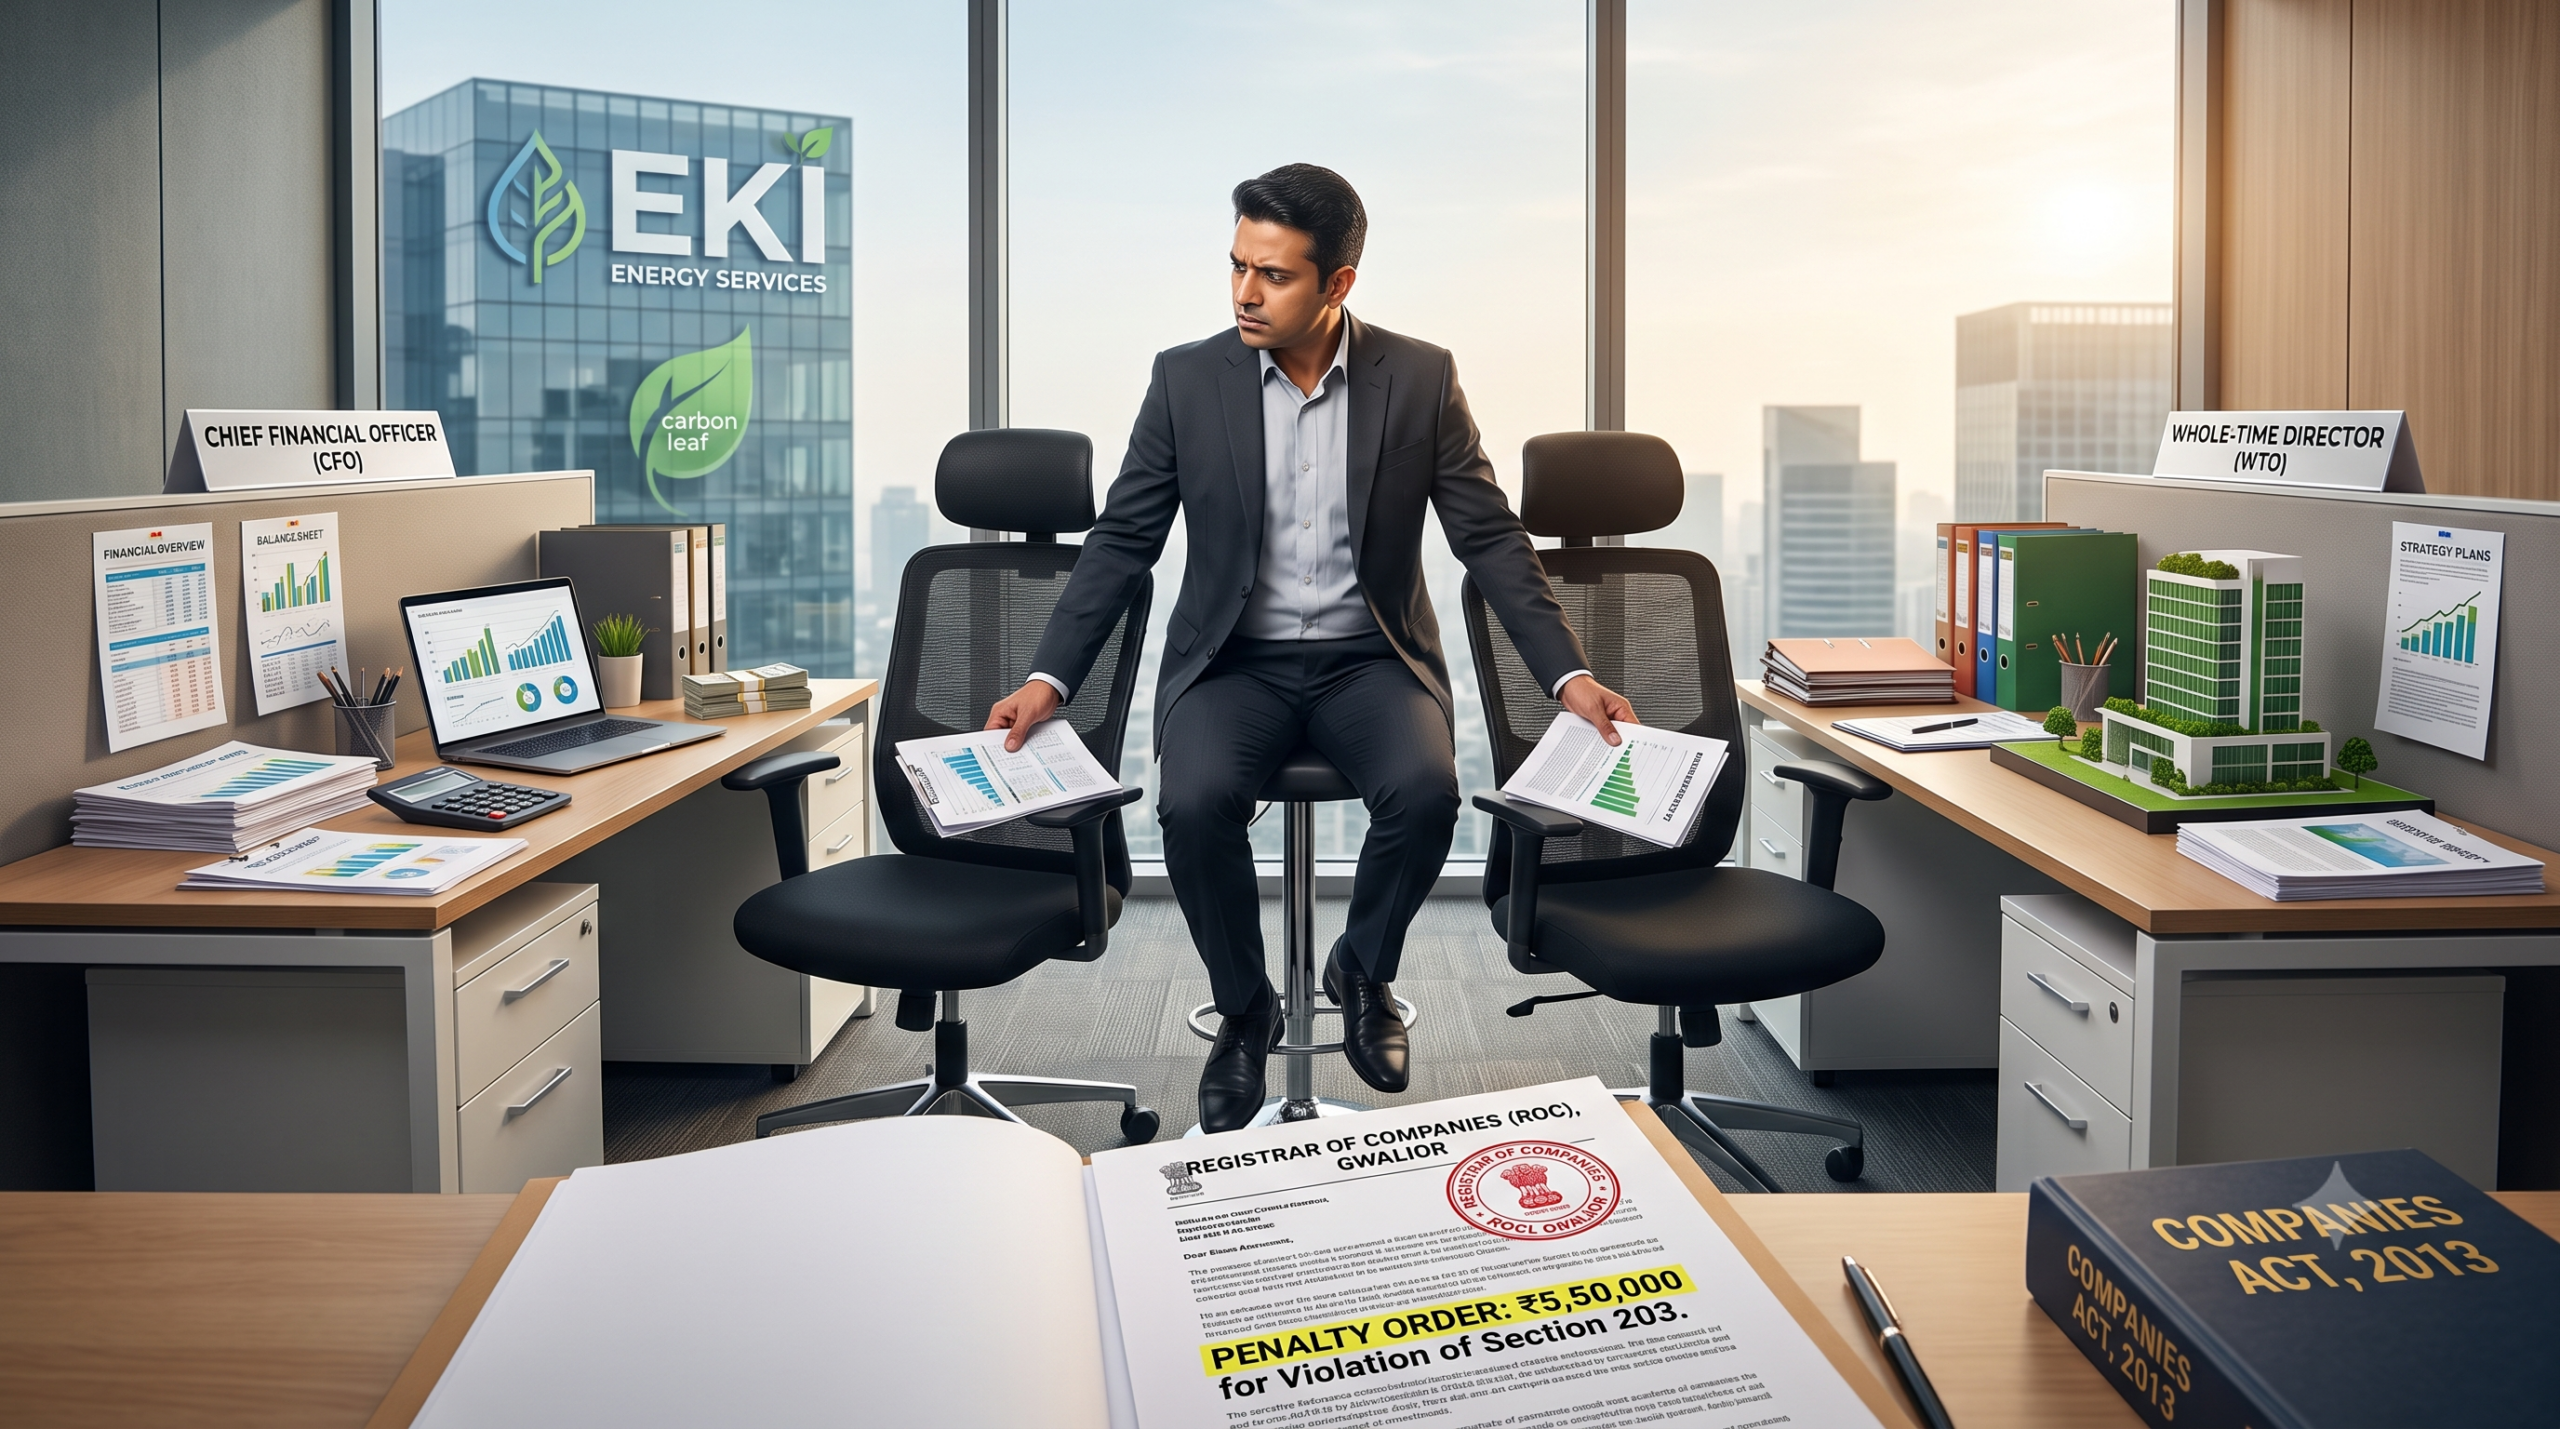
    Can your CFO also run the company? A ₹5.5 lakh order from ROC Gwalior says no — but the statute may not say that at all.


    Why This Order Should Make Every Company Secretary Nervous

    Here is a question that sounds almost too simple to litigate: can one person be both the finance chief and a whole-time director of the same company?

    Most Indian promoters would answer instinctively — “why not, he’s competent, he’s trusted, why hire a second person to do a job one person can already do well?” Company secretaries across the country have, for over a decade, quietly gone along with exactly this arrangement in closely-held and promoter-driven listed companies. It has never been expressly forbidden anywhere in the Companies Act, 2013.

    On 29 June 2026, the Registrar of Companies, Gwalior, told EKI Energy Services Limited — the Indore-headquartered, BSE-listed carbon-credit major that built its reputation on rigorous environmental compliance — that this common assumption is wrong. The company was penalised ₹5,00,000 and its Managing Director ₹50,000 for appointing Mr. Mohit Kumar Agarwal simultaneously as Chief Financial Officer and Whole-Time Director, without appointing a separate person to head the finance function (EKI Energy Adjudication Order, ROC Gwalior, Order ID PO/ADJ/06-2026/GL/02450, dated 29.06.2026).

    The order is short — barely five substantive paragraphs — but it sits on top of a genuine, long-running, and largely unresolved interpretive fault line in Section 203 of the Companies Act, 2013. This piece walks through that fault line: what the statute actually says, what ROC Gwalior read into it, where the order is analytically strong, where it is vulnerable to challenge, and what companies — especially the hundreds of small and mid-cap listed entities that run lean management teams — should do differently starting today.

    1. The Order at a Glance

    ParticularsDetail
    CompanyEKI Energy Services Limited, CIN L74200MP2011PLC025904
    Provision violatedSection 203(1) read with Section 203(5), Companies Act, 2013
    TriggerInspection under Section 206(5); Form MGT-14 (SRN AB2323516, dated 03.01.2025) for appointment of Mr. Mohit Agarwal as Additional Director designated Whole-Time Director, while he continued as CFO
    Show Cause NoticeSCN/ADJ/06-2026/GL/04667 dated 03.06.2026
    Penalty on company₹5,00,000
    Penalty on officer in default₹50,000 (Mr. Manish Kumar Dabkara, Managing Director, designated Officer in Default under Section 2(60) vide Board Resolution dated 26.03.2021 and Form GNL-3, SRN ABB641577)
    Penalty on Mr. Mohit Agarwal (the individual who held both offices)₹0
    Appeal forumRegional Director, Ahmedabad, within 60 days, in Form ADJ (Section 454(5) & (6))

    That last row is not a typo, and we will return to it — it is one of the more interesting quirks buried in this order.

    2. The Statutory Architecture: What Section 203 Actually Requires

    Section 203(1) of the Companies Act, 2013 obliges every company of a prescribed class to appoint the following whole-time key managerial personnel:

    • managing director, or Chief Executive Officer or manager, and in their absence, a whole-time director;
    • a company secretary; and
    • a Chief Financial Officer.

    The class of companies covered is fixed by Rule 8 of the Companies (Appointment and Remuneration of Managerial Personnel) Rules, 2014 — every listed company, and every other public company with paid-up share capital of ₹10 crore or more. EKI Energy, a BSE-listed company with paid-up capital well above that threshold, squarely falls within this bracket.

    Two textual features of Section 203 matter enormously for this dispute:

    First, the whole-time-director slot in Section 203(1)(i) is explicitly conditional — it is required only “in their absence”, i.e., in the absence of a managing director, CEO, or manager. Where a company already has a Managing Director, the Act does not mandate a separate Whole-Time Director at all.

    Second, Section 203(3) provides that a whole-time KMP “shall not hold office in more than one company except in its subsidiary company at the same time.” Read literally, this restriction is about one person holding the same KMP office in multiple companies simultaneously — not about one person holding two different KMP offices within the same company.

    Nowhere in the plain text of Section 203 does the Act say, in so many words, that the CFO and the Whole-Time Director must be different individuals. This absence is the crux of the entire debate, and industry commentary has flagged it for over a decade — one widely cited professional commentary on Section 203 observes that there is nothing in the section which expressly debars the same person from holding the office of CFO and Managing Director simultaneously, and even draws a contrary inference from the wording of sub-section (3) (CAclubindia, “Appointment of Key Managerial Personnel under Section 203 — Some Perspectives,” 2014).

    3. What ROC Gwalior Actually Held

    The Adjudicating Officer rejected the company’s defence — that there is no express statutory bar — on essentially purposive grounds. The order reasons that Section 203(1) contemplates distinct categories of whole-time KMP carrying separate statutory responsibilities for governance and management, that the underlying legislative intent is to secure segregation of key managerial functions and accountability, and that collapsing the CFO and Whole-Time Director roles into one individual — without filling the CFO vacancy separately — defeats that purpose (EKI Energy Adjudication Order, Part E.1). The order also dismissed the argument that similar arrangements exist elsewhere in the market, holding that a widespread practice cannot legitimise a statutory non-compliance, since every company independently owes the obligation to comply.

    That is a coherent policy argument. Whether it is a sound reading of the statute as drafted is a separate question — and this is where the order becomes genuinely contestable.

    4. Is There Really a Bar? The Interpretive Debate

    4.1 The textualist objection

    Indian courts and tribunals have long insisted that penal and quasi-penal provisions — and a Section 454 monetary penalty is unmistakably punitive in character — must be construed strictly, with any real ambiguity resolved in favour of the party facing the penalty rather than the regulator. Section 203, as drafted, restricts multi-company holding of whole-time KMP office (sub-section 3) and separately restricts the Chairperson from simultaneously holding the MD/CEO post unless the articles permit it or the company does not carry on multiple businesses (first proviso to sub-section 1). In other words, when Parliament wanted to bar one individual from holding two specific roles at once, it said so explicitly — for Chairperson-and-MD/CEO. It did not extend an equivalent express bar to CFO-and-Whole-Time-Director. Under the interpretive canon of expressio unius est exclusio alterius (the express mention of one thing excludes others), the absence of a similar express bar for CFO/WTD combinations is not an oversight to be cured by the regulator through purposive reasoning — it is a legislative choice.

    4.2 The purposive response

    The counter-argument is equally respectable. Section 2(19) defines the CFO as a distinct statutory office with its own certification duties (e.g., under Section 134(5) read with the CEO/CFO certification requirement borrowed from erstwhile clause 41/49 of the listing agreement and now under SEBI’s Listing Obligations and Disclosure Requirements framework), and Section 203’s very structure — listing MD/CEO, CS, and CFO as three separate whole-time offices — signals an intent that financial stewardship should not be self-supervised by the same individual who also runs day-to-day operations as an executive director. On this reading, “whole-time” itself is doing textual work: a genuinely whole-time CFO cannot simultaneously discharge a genuinely whole-time directorial mandate, because the definitional premise of both offices is full-time, undivided attention.

    4.3 What the precedents actually say

    The case law here is thinner than the volume of ROC adjudication orders would suggest, and none of it addresses the exact CFO-and-WTD fact pattern head-on — which is itself telling.

    • NCLAT, Hamlin Trust and Others v. LSF10 Rose Investments and Others (concerning the CFO appointment at Rattan India Finance Private Limited), Company Appeal (AT) No. 77 of 2022, order dated 7 September 2022, set aside an NCLT Delhi order and held that once a company chooses to designate an individual as CFO, that appointment must comply with Section 203 dehors any contrary provision in the articles, because the CFO is a KMP under Section 2(51) (Cyril Amarchand Mangaldas, “Key Managerial Personnel Appointments… does the NCLAT order cast the net too wide?”, 12 October 2022). The Tribunal’s underlying approach is functional — it looks at what the appointee actually is, not merely at what the company chooses to call the arrangement — which cuts in ROC Gwalior’s favour on the general proposition that KMP status and its attendant obligations cannot be structured around.
    • A Registrar of Companies order on Landomus Realty Private Limited, dated 7 February 2022, took a similarly strict, form-over-substance-be-damned approach: even where a private company was not statutorily required to appoint a CEO under Section 203, using the designation “CEO” without a board resolution and without filing Form DIR-12 was itself held to violate the Act (Cyril Amarchand Mangaldas, ibid.). This suggests regulators are, as a matter of enforcement trend, increasingly unwilling to let informal or hybrid designations escape statutory scrutiny — a trend the EKI order fits into.
    • On the appellate side, the Regional Director (Eastern Region), in the Delta International Limited appeal arising from a Kolkata ROC’s Section 203 order, overturned penalties imposed on independent directors, reasoning that liability under Section 203 read with Section 454 must track actual responsibility for the default and cannot be mechanically extended to directors who had no functional role in the contravention (Taxmann, “Justice Served: RD Overturns Penalty on Independent Directors…”, 5 September 2024). That order is instructive for EKI’s own facts: it supports the idea adjudicating and appellate authorities do engage in a granular, responsibility-based analysis rather than treating every officer as equally culpable — which is relevant to why, as discussed below, Mr. Agarwal himself was not penalised in the EKI order.

    None of these precedents squarely rules on whether one individual may simultaneously hold CFO and Whole-Time Director office in the same company where an MD already exists. That question remains, as of this writing, adjudicated only at the level of a Registrar’s order — not yet tested before the National Company Law Tribunal, NCLAT, or a High Court.

    5. Prevailing Practice: This Is More Common Than the Order Suggests

    Anecdotally and in professional literature, dual-hatting of KMP roles is widespread, particularly in:

    • Founder-led and promoter-driven companies, where a trusted finance professional is elevated to the board as an Executive/Whole-Time Director while retaining CFO responsibilities, often to reward loyalty or to avoid diluting control by inducting an outside executive to the board.
    • Small and mid-cap listed companies that recently crossed the Rule 8/8A thresholds (paid-up capital ₹10 crore) and are still building out a full KMP bench — ROC adjudication data from FY 2024-25 shows a steady stream of orders for outright non-appointment of a CFO or Company Secretary, reflecting genuine capacity constraints at this end of the market (MMJC, “ROC enforcement trend in FY 2024-25,” 2026).
    • Group/holding structures, where the same individual carries designations across the parent and subsidiary, though Section 203(3)’s subsidiary carve-out expressly permits this at the inter-company level.

    The company’s own submission in the EKI order — that “similar practice may be followed by other companies” — was not fabricated; it reflects a real, if legally unexamined, market convention. The ROC’s response, that a widespread practice cannot cure non-compliance, is legally unimpeachable as a general proposition, but it sidesteps the harder question of whether the practice is non-compliant at all in the first place.

    6. The Overlooked Fact Pattern: Grounds on Which This Order Is Vulnerable

    This is where the EKI order’s own recitals work against its conclusion, and where a genuine appeal ground emerges.

    6.1 EKI already had a Managing Director

    Section 203(1)(i) mandates a Whole-Time Director only “in their absence” — i.e., in the absence of a managing director, CEO, or manager. The order itself records that Mr. Manish Kumar Dabkara was designated Managing Director and Officer in Default pursuant to a Board Resolution dated 26 March 2021, filed via Form GNL-3 (SRN ABB641577). If EKI already had a functioning Managing Director occupying the Section 203(1)(i) slot, then the statutory mandate for a Whole-Time Director was never triggered in the first place — the company’s obligation under 203(1)(i) stood discharged by Mr. Dabkara’s MD appointment alone.

    On this reading, Mr. Agarwal’s designation as Whole-Time Director was not filling a mandatory Section 203 vacancy; it was an additional, voluntary executive directorship layered on top of an already-compliant structure. If that is correct, the ROC’s “segregation of functions” rationale loses much of its force: there was no statutory CFO-or-WTD slot left unfilled or improperly doubled up, because the mandatory MD/WTD slot was independently and separately satisfied by Mr. Dabkara. What EKI actually did was appoint one CFO (Agarwal, satisfying 203(1)(iii)) and one MD (Dabkara, satisfying 203(1)(i)) — textbook compliance — and then, separately, gave Mr. Agarwal an additional board seat and title that happened to include the words “Whole-Time Director.”

    The counter to this counter is that once a person is formally designated a “whole-time director” — regardless of whether that designation was strictly necessary under 203(1)(i) — he becomes a whole-time director as defined in Section 2(94) (a director in the whole-time employment of the company) and therefore automatically a KMP under Section 2(51)(iii), by force of definition rather than by statutory mandate. If the ROC’s “no dual whole-time KMP office” principle is accepted at all, it would arguably apply regardless of whether the WTD slot was mandatory or voluntary. But this only sharpens the underlying interpretive question raised in Section 4 above — it does not resolve it, because Section 203(3)’s express bar remains confined to multi-company holding, not multi-office holding within one company. The company’s strongest ground of appeal, in other words, is not merely “the market does this too,” but a textual argument that was raised before the Adjudicating Officer yet was not engaged with in the order’s reasoning at all: the statutory need for a Whole-Time Director never arose on these facts, because a Managing Director was already in place.

    6.2 The unexplained ₹0 penalty on the actual dual-office holder

    Under Section 2(60)(ii) of the Act, any key managerial personnel is, by definition, an “officer who is in default.” Mr. Agarwal, as CFO (and, on the ROC’s own reasoning, impermissibly, as WTD too), would ordinarily fall squarely within that definition for a contravention of Section 203. Yet the penalty table imposes ₹0 on him, while imposing ₹50,000 on Mr. Dabkara, who was separately designated Officer in Default under the residuary limb of Section 2(60) via Form GNL-3. The order does not explain this allocation. A plausible reading is that the Adjudicating Officer treated the underlying default — the Board’s decision to appoint one person to both offices — as attributable to the company’s collective decision-making (and hence to the designated Officer in Default and the company itself) rather than to Mr. Agarwal personally, since he did not appoint himself. If that reasoning holds, it is at least in some tension with the strict, KMP-triggers-automatic-liability logic that Section 2(60)(ii) otherwise contemplates, and would itself be a fair target for scrutiny on appeal — by either side.

    7. Constructive Criticism: A Fair Assessment, Not Just a Defence Brief

    To be even-handed, the order is not without merit, and companies should not read the above as a green light to dual-hat CFO and WTD roles:

    • The purposive reading has real institutional support. SEBI’s corporate governance framework and the broader thrust of Chapter XIII of the Act (KMP appointment, remuneration, and accountability) plainly favour functional segregation between financial stewardship and executive management, especially in listed companies where public shareholders rely on an independent CFO signature on financial statements.
    • The “whole-time” qualifier is not decorative. Even absent an express textual bar on holding two KMP offices, a genuine question survives about whether one individual can, as a matter of fact rather than law, discharge two “whole-time” statutory roles simultaneously and in good faith certify both functions independently of each other — a concern the ROC’s order gestures at but does not fully develop.
    • The order’s failure to engage the “MD-already-in-place” argument is a real gap, not because the ROC’s ultimate conclusion is necessarily wrong, but because an adjudicating authority imposing a monetary penalty ought to squarely address the strongest textual defence raised, rather than resolve the matter purely at the level of legislative purpose.
    • The regulatory direction of travel — visible in the Rattan Finance and Landomus precedents — is toward stricter, function-first scrutiny of KMP designations. Even if this particular order is successfully appealed on its specific facts, companies should not expect the underlying tolerance for dual-hatting to persist indefinitely.

    8. Course Correction: A Practical Checklist for Companies

    1. Audit every KMP appointment against Section 203(1) before filing MGT-14. Confirm, in writing, whether the individual is filling a mandatory slot or an additional/voluntary one, and record the board’s reasoning.
    2. Never combine CFO with any other KMP or executive-director designation unless a documented legal opinion has been obtained and placed on record with the Board minutes — the cost of an opinion is trivial next to a ₹5 lakh penalty plus reputational exposure for a listed company.
    3. Where a Managing Director or CEO already exists, think twice before layering on a “Whole-Time Director” title for a KMP — if the intent is purely to reward or formalise a senior executive’s board presence, consider a Non-Executive/Executive Director designation that does not risk automatic KMP overlap, or ensure the CFO function is separately and genuinely staffed.
    4. Revisit the Officer-in-Default designation under Section 2(60) at every AGM cycle, particularly after any KMP restructuring, so that liability allocation among directors, KMP, and the company reflects current facts rather than a stale board resolution.
    5. Build a standing KMP register cross-check into the secretarial audit calendar (Section 204) — this is precisely the kind of latent, easily-overlooked default that a Section 206 inspection, rather than routine filings review, tends to surface years after the fact, by which time continuing-default exposure (up to the ₹5 lakh cap) has already accrued.
    6. If already in a dual-hat arrangement, rectify promptly and document the rectification date — Paragraph 3 of the EKI order itself requires notified officers to rectify the default and pay the applicable penalty within 90 days, and continuing-default penalties are calculated with reference to the rectification date.

    9. Conclusion

    The EKI Energy order will likely be cited for years as one of the clearest ROC pronouncements against combining the CFO and Whole-Time Director roles in one individual. But “clearest” is not the same as “unappealable.” The order rests on a purposive reading of Section 203 that is defensible in policy terms yet leaves unaddressed a squarely textual defence — that the company’s Managing Director had already discharged the Section 203(1)(i) obligation, making the Whole-Time Director designation additional rather than a second mandatory KMP office in genuine conflict with the CFO role. Whether that argument succeeds before the Regional Director, Ahmedabad, within the 60-day appeal window, or eventually before the NCLT/NCLAT, will do more to settle this question than the order itself has managed to. Until then, the safest compliance posture for every company caught in a similar structure is to assume the stricter reading will prevail — and to separate the two chairs before a Section 206 inspection does it for you.


    References

    1. Companies Act, 2013 — Sections 2(19), 2(51), 2(60), 2(94), 203, 206, 454.
    2. Companies (Appointment and Remuneration of Managerial Personnel) Rules, 2014 — Rule 8, Rule 8A.
    3. Companies (Adjudication of Penalties) Rules, 2014.
    4. Registrar of Companies, Gwalior, Order for Adjudication of Penalty under Section 454… for Violation of Section 203(5), Order ID PO/ADJ/06-2026/GL/02450, dated 29 June 2026 (In the matter of EKI Energy Services Limited).
    5. National Company Law Appellate Tribunal, Hamlin Trust and Others v. LSF10 Rose Investments and Others, Company Appeal (AT) No. 77 of 2022, order dated 7 September 2022.
    6. Registrar of Companies order in the matter of Landomus Realty Private Limited, dated 7 February 2022.
    7. Regional Director (Eastern Region), appellate order in the matter of Delta International Limited (arising from ROC Kolkata order dated 8 November 2023 under Section 203/454).
    8. “Appointment of Key Managerial Personnel under Section 203 of the Companies Act, 2013 — Some Perspectives,” CAclubindia, 2014.
    9. “Key Managerial Personnel Appointments: Applicability of Section 203… does the NCLAT order cast the net too wide?”, India Corporate Law (Cyril Amarchand Mangaldas Blog), 12 October 2022.
    10. “ROC enforcement trend in FY 2024-25 — A deep dive into adjudication and decisions,” MMJC & Associates, 2026.
    11. “Opinion: Justice Served — RD Overturns Penalty on Independent Directors…”, Taxmann, 5 September 2024.

    This article is intended for general legal awareness and academic discussion only. It does not constitute legal advice and should not be relied upon as a substitute for independent legal counsel on the specific facts of any matter, including in relation to any appeal against the order discussed above.